A gold retirement account, commonly known as a gold IRA or a self-directed particular person retirement account, is a specialised funding car that allows you to hold bodily valuable metals as a part of your tax-advantaged retirement portfolio. Not like traditional IRAs that hold paper property such as stocks and bonds, a gold retirement account is designed to carry tangible metallic assets. Investors are sometimes drawn to those accounts as a technique to diversify beyond paper assets and to hunt potential protection towards inflation and currency risk. While the idea is simple, the mechanics, prices, and guidelines are more intricate than a typical IRA, demanding careful planning and professional steerage.
At its core, a gold retirement account operates underneath the same tax framework as different IRAs. The account is established with a custodian or trustee that specializes in self-directed plans. The custodian is chargeable for account administration, compliance with IRS guidelines, and reporting, while a separate, insured depository stores the physical metals. You don't personal and home the steel in your house; as a substitute, the metallic is held in safe storage in your behalf and is insulated from most private dangers of possession. The investment could be funded by means of a rollover, switch, or new contribution, topic to annual contribution limits and eligibility rules. In addition to the gold option, many self-directed IRAs permit other treasured metals, real property, and alternative belongings, but tax and custody guidelines differ by asset class. The result's a retirement account that blends traditional tax advantages with the potential stabilization benefits of gold.
A traditional gold IRA and a Roth gold IRA illustrate how tax treatment impacts investing choices. With a traditional Gold IRA, contributions could also be tax-deductible, and growth compounds tax-deferred till withdrawal, at which point distributions are taxed as abnormal revenue. A Roth Gold IRA, by contrast, uses after-tax contributions, and qualified withdrawals in retirement are tax-free. The choice between Traditional and Roth depends in your current tax fee, expected future tax charges, and timing of retirement plans. It can be crucial to consider how gold’s value habits interacts with other assets in a retirement plan and how tax timing can affect after-tax outcomes over a long time. Importantly, distributions of the metallic itself observe the identical tax principles as cash distributions: bizarre earnings for Traditional accounts, and generally tax-free for certified Roth withdrawals, topic to IRS rules and the duration of the account.
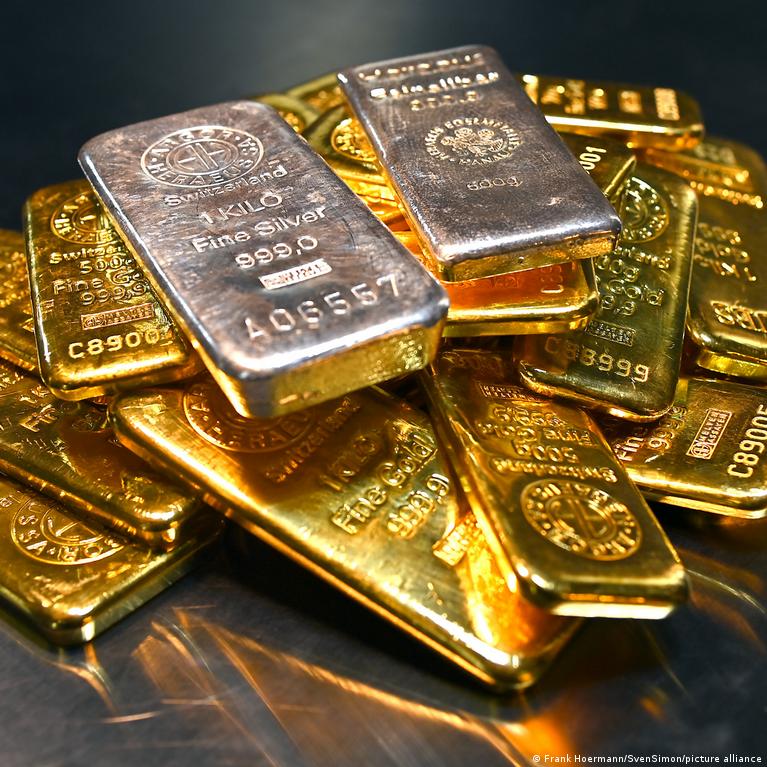
Certified metals and eligibility kind a important a part of any gold retirement account. The IRS restricts holdings to sure precious metals that meet outlined fineness and minting requirements. In follow, buyers typically choose gold coins and bars produced by acknowledged mints or refiners. Widespread choices embrace authorities-minted coins and refined bars that meet minimum fineness requirements, often around 99.5% gold or higher, and produced by reputable, IRS-accepted sources. Examples of extensively available choices embrace authorities-issued coins such as the American Gold Eagle or the Canadian Gold Maple Leaf, as well as bars from established refiners. Not each gold product qualifies; some coins and merchandise are thought of collectibles or don't meet the desired fineness or authenticity standards and can't be held in a Gold IRA. The custodian and depository will verify eligibility before accepting any metal into the account.
Funding and ownership stream by means of distinct steps. After deciding on a professional custodian, you determine the right way to fund the account—via rollover from a prior IRA or 401(ok), a switch from one other retirement account, or a new contribution topic to yearly limits. Rollovers and transfers must comply with IRS timelines and avoid triggering tax consequences or penalties. Once funds are within the account, you work with the custodian to buy IRS-certified precious metals from authorized sellers. The bought metals are then shipped on to an insured, IRS-approved depository chosen by you or the custodian. This depository holds the metallic in segregated storage or in pooled arrangements, relying on the supplier, and carries ongoing insurance coverage. The investor retains possession of the metal but retains no physical possession, which helps preserve compliance with IRS guidelines and protects the asset towards personal loss or damage.
Prices are a central consideration for any gold retirement plan. The price of entry and ongoing expenses will be increased than traditional paper IRAs on account of specialised storage, insurance, and administration. Typical value elements embody setup or account-opening charges, annual maintenance or advisory charges charged by the custodian, storage and insurance costs levied by the depository, shipping or delivery charges for preliminary acquisition, and potential transaction spreads when metals are purchased or sold. Some custodians charge a flat annual payment, while others assess a proportion of property beneath administration. Because prices can compound over a few years, it is crucial to acquire a detailed, written price schedule before committing to a Gold IRA. It is also prudent to check the all-in price over a multi-yr horizon quite than focusing solely on upfront or per-transaction expenses. While storage fees may be modest in percentage terms, they accumulate because the account worth grows, and it is best to issue them into the expected price of return over time.
Investing in a gold retirement account provides several potential benefits, but it surely additionally comes with trade-offs. Proponents highlight diversification benefits, the potential for gold to retain worth during periods of high inflation or foreign money weakness, and the potential for lowering portfolio volatility by exposure to a non-correlated asset class. As well as, some buyers view gold as a protracted-time period store of value that doesn't rely on credit risk or corporate efficiency. On the flip side, gold costs may be risky, and there isn't any guaranteed upside. As a result of gold is not producing revenue like dividends, the return of a Gold IRA rests completely on value appreciation or depreciation and the avoidance of excessive storage and transaction prices. Liquidity is mostly strong for widely held types of bullion and coins, however the strategy of liquidation inside an IRA can contain extra fees and time, significantly if the custodian must coordinate with the depository and ensure compliance with IRS guidelines.
Several practical concerns influence whether or not a gold retirement account is appropriate for you. First, evaluate your funding time horizon and threat tolerance. An extended horizon and a willingness to absorb short-term price swings could be conducive to gold exposure. Second, assess the total value of ownership, including custody, storage, insurance, and potential exit charges, and examine it to various inflation hedges or diversification methods. Third, look at your present retirement plan, tax scenario, and estate planning goals. Gold IRAs can complicate withdrawals and beneficiary designations, so understanding the distribution rules and potential tax implications is crucial. Fourth, consider the accessibility of skilled guidance. The regulatory panorama for self-directed accounts is complex, and the standard of custodians and depositories varies. Working with financially licensed professionals may also help guarantee correct setup, ongoing compliance, and clear price structures.
The setup course of for a gold retirement account may be simple, however it advantages from careful planning. A practical checklist includes: selecting a good custodian experienced in self-directed IRAs and valuable metals; confirming IRS compliance of the metals to be held; selecting an IRS-accepted depository and arranging segregated storage if desired; arranging funding by way of rollover, switch, or contribution; acquiring a transparent, itemized fee settlement; understanding the withdrawal and distribution guidelines for both Conventional and Roth accounts; and establishing a beneficiary plan and property concerns. Investors must also verify insurance coverage coverage levels offered by the depository and confirm the process for in-kind distributions if they ever resolve to redeem or take possession of the physical metals at retirement.
In summary, a gold retirement account affords a distinct pathway to diversify a retirement portfolio by incorporating physical gold throughout the favorable tax framework of an IRA. It combines the tax benefits of self-directed accounts with the potential inflation-hedging properties of valuable metals, while introducing unique costs, custody responsibilities, and regulatory requirements. Prospective traders ought to approach a Gold IRA with a clear understanding of the eligibility standards for metals, the position of the custodian and Iouel depository, the related charges, and the long-run implications for retirement planning. A effectively-informed choice includes cautious comparability of providers, transparent disclosure of all fees, and alignment with long-term monetary objectives. When built-in thoughtfully, a gold retirement account can complement different property in a holistic technique, providing an additional tool to weather economic cycles whereas pursuing retirement security.