 How does an underwriter assess a contractor's risk?
Underwriters assess a contractor's risk by evaluating their financial stability, project experience, compliance with regulations, and the quality of their documentation. This comprehensive assessment helps determine the likelihood of project completion and the potential for financial loss.
When weighing the pros and cons of obtaining construction bonds, it's essential to consider both the advantages and potential drawbacks. While the benefits of increased credibility and access to larger projects are significant, the costs and time involved in securing these bonds should not be overlooked. A balanced approach can help contractors make informed decisions regarding their bonding needs.
 In addition to documenting the change orders themselves, keeping a record of communications related to the changes is equally important. For additional context, visit how Construction Bonding Works for a quick breakdown of the essentials. This includes emails, meeting notes, and any other correspondence that can clarify the context and rationale behind each decision. Such a paper trail can be invaluable in case disputes arise, providing evidence that can help resolve conflicts amicably.
Understanding the Application Process
The application process for obtaining a surety bond can vary significantly between providers. Typically, it involves submitting financial documents, business information, and project details to the surety company for underwriting. Understanding this process, and the timeline involved, can help you plan accordingly and avoid any delays in acquiring your bond.
What should contractors do if a client disputes a change order?
Contractors should refer to the documentation and communication records related to the change order. Open dialogue and negotiation can often resolve disputes before escalating to legal action.
Conclusion
In conclusion, successfully navigating the world of construction bonds requires a comprehensive understanding of the various types of bonds, financial preparedness, and effective project management. By focusing on these key areas, contractors can significantly improve their chances of impressing surety companies and securing necessary bonds for their projects. Building strong relationships with surety agents and maintaining a solid portfolio are also crucial for long-term success.
 Can I get a bond if I have a poor credit score?
While a poor credit score may hinder your chances of securing a bond, it is not impossible. Some sureties work with contractors with lower credit scores, but you may need to provide additional collateral or demonstrate improved financial practices.
Can I increase my bonding capacity?
Yes, subcontractors can increase their bonding capacity by maintaining good financial practices, improving credit ratings, and submitting to regular reviews with their surety company.
Legal and Regulatory Compliance
Compliance with legal and regulatory standards is another significant factor underwriters scrutinize. Contractors must demonstrate awareness of local, state, and federal laws that pertain to construction projects. This includes obtaining the necessary permits, licenses, and adhering to safety regulations. Failure to comply can lead to costly delays and penalties, posing a risk to the underwriter's investment in the project.
This table provides a quick reference to the various types of construction bonds, their purposes, and the key requirements needed to secure them. Understanding these elements can aid contractors in preparing effective applications and enhancing their chances for success.
Furthermore, utilizing technology can enhance reporting capabilities. To expand on this point, see how Construction Bonding Works for a useful checklist and notes. Investing in accounting software or financial management tools can streamline data collection and reporting processes. These tools can generate real-time reports that provide insights into the business's financial status, allowing for timely adjustments that can impact bond rates positively.
 Can I get a surety bond with bad credit?
Yes, it is possible to obtain a surety bond with bad credit, but the cost may be higher. Some providers specialize in working with contractors who have less-than-perfect credit histories, so it’s worth exploring those options.
Frequently Asked Questions
What is a construction bond?
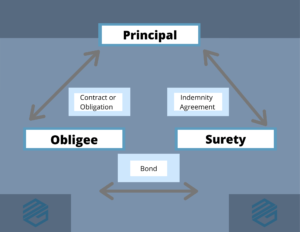
A construction bond is a contractual agreement that provides a guarantee that a contractor will fulfill their obligations to complete a project as promised. These bonds protect project owners from financial losses due to contractor default.
When presenting your portfolio to sureties, emphasize projects that align with the type of work you wish to pursue in the future. Tailoring your portfolio to the specific needs of each surety company can improve your chances of bond approval.
 In the world of construction, managing change orders effectively is crucial for the success of any project, especially in bonded construction work. Change orders can arise from various factors such as unforeseen circumstances, design modifications, or client requests. Understanding how to navigate these changes while minimizing disruptions can significantly impact a project's timeline and budget. This article delves into strategies for handling change orders efficiently, ensuring that both contractors and clients remain satisfied.