In summary, understanding the intricacies of construction bonds and the implications of claims is essential for all stakeholders in the construction industry. These bonds serve as critical tools for risk management, providing security and assurance to project owners while enhancing the credibility of contractors. The claim process, while complex, is designed to protect all parties involved, ensuring that obligations are met and financial losses are mitigated. By navigating the world of construction bonds with informed strategies and thorough documentation, stakeholders can foster a more collaborative and secure construction environment. Ultimately, knowledge is power, and understanding these dynamics can lead to better project outcomes and long-term success in the construction sector.
 Another effective strategy is to establish strong relationships with suppliers and subcontractors, as this can enhance overall project performance, further improving creditworthiness. By showcasing reliability and financial stability, contractors can position themselves favorably during the bonding process, thereby reducing costs.
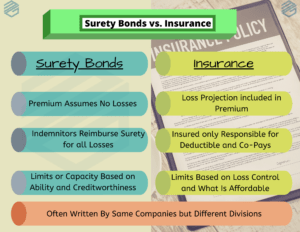
 Implementing strong financial management practices can significantly reduce risks and enhance a contractor's ability to secure bonding in the future. Additionally, contractors should consider diversifying their project portfolio to avoid over-reliance on a single client or project, which can lead to financial instability.
Payment Bonds: Protecting Subcontractors and Suppliers
Payment bonds are essential for ensuring that all parties in the construction process are compensated for their work. For more perspective, see surety bonds for construction projects for a useful checklist and notes. These bonds protect subcontractors and suppliers from payment defaults, ensuring they receive their dues for services rendered. In many states, payment bonds are required by law for public projects, providing a safety buffer for subcontractors who might otherwise be left at risk.
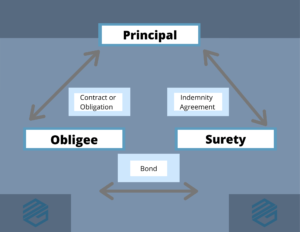
 Once the surety has evaluated the claim, they may choose to settle the claim directly with the obligee or deny the claim, citing insufficient evidence or other reasons. If the claim is settled, the surety will disburse funds to cover the losses incurred by the obligee. However, if the claim is denied, the obligee has the option to pursue further legal action. Understanding these processes can help all parties navigate the complexities of claims efficiently and effectively.
 In the ever-competitive world of construction, winning client loyalty is paramount for sustained success. One effective way to achieve this is through bonded construction work, a strategy that not only builds trust but also enhances the reputation of a construction company. By leveraging bonding mechanisms, contractors can assure clients of their commitment to quality and reliability, which significantly influences the likelihood of repeat business. This article will explore various dimensions of bonded construction work, emphasizing its impact on client relationships and business growth.
 In this article, we will explore various aspects of bonded construction work, focusing on the ten critical red flags that can kill your bonding. These signs range from issues related to project management and contractor reliability to compliance with industry standards. By the end of this discussion, you will have a comprehensive understanding of what to look for, enabling you to make informed decisions before engaging with contractors in bonded projects.
Participating in industry networking events and joining professional organizations can also help contractors connect with surety representatives. When contractors demonstrate their commitment to the industry and their willingness to engage with surety companies, they are more likely to be considered for higher bonding limits. Establishing a mutually beneficial relationship can lead to enhanced bonding opportunities and, ultimately, greater project success.
In weighing the pros and cons, it is essential to recognize that while enhancing bonding capacity offers significant benefits, it also introduces new challenges. To expand on this point, see surety bonds for construction projects for a quick breakdown of the essentials. Contractors must balance their aspirations with the realities of maintaining compliance, managing finances, and delivering quality work. However, with the right strategies in place, the advantages can far outweigh the drawbacks, leading to sustainable growth and success in the construction industry.
 Furthermore, utilizing project management software can enhance communication and transparency. To expand on this point, see surety bonds for construction projects for related insights and background. These tools provide real-time updates and allow for better tracking of project milestones. If a contractor is resistant to implementing such technologies, it may indicate a reluctance to maintain transparency throughout the project's lifecycle.
Moreover, maintaining open communication with all stakeholders, including clients, subcontractors, and suppliers, is essential for project success. To compare approaches, take a look at surety bonds for construction projects to see common pitfalls and fixes. Regularly updating stakeholders on project progress and addressing any issues promptly can foster a collaborative environment, ultimately leading to successful project completion. This reliability can enhance a contractor's reputation and bonding capacity.