 Leveraging Technology for Business Growth
In today's digital age, leveraging technology can give contractors a competitive advantage in securing larger jobs. To compare approaches, take a look at construction bonding documentation tips for a quick breakdown of the essentials. Utilizing project management software can enhance efficiency by streamlining operations, improving communication, and tracking progress. Additionally, adopting marketing strategies that include a strong online presence can help contractors reach a broader audience.
Qualifying for Larger Construction Jobs
To qualify for larger construction jobs, contractors need to meet specific criteria set by project owners and bonding companies. One of the primary factors is the contractor's experience level. Owners often prefer contractors with a proven track record of successfully completing projects of similar size and complexity. Therefore, building a robust portfolio showcasing past projects is essential for contractors looking to secure larger jobs.
 Strategies for Streamlining Paperwork in Bonded Construction Work
To facilitate faster payments in bonded construction work, contractors must implement effective strategies for managing paperwork. One of the first steps is to use project management software that allows for seamless documentation and communication among all parties involved. These platforms can help organize contracts, invoices, and other essential documents, ensuring that everything is accessible and up to date. Utilizing technology can significantly reduce the time spent on paperwork and enhance overall efficiency.
Implementing Risk Management Strategies
Effective risk management is a critical component of a surety-friendly operation. Contractors must identify potential risks associated with their projects and develop strategies to mitigate them. This proactive approach not only helps in maintaining financial stability but also showcases to sureties that the contractor is serious about managing risks.
Understanding the Importance of Bonding in Construction
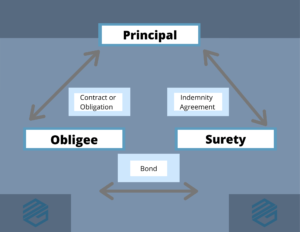
Bonding serves as a critical assurance for project owners, ensuring that contractors will complete their work as agreed. A bond is essentially a guarantee that provides financial protection to the project owner in case the contractor fails to fulfill their obligations. This safety net is vital for clients, particularly for larger projects where the stakes are higher. Contractors who are bonded can gain a competitive edge, as it demonstrates their commitment to quality and reliability.
Contractors should prioritize open dialogue with clients to understand their expectations and address any concerns promptly. Additionally, nurturing relationships with subcontractors and suppliers ensures a reliable network that contributes to project success. Establishing rapport with surety companies can also facilitate smoother bond acquisition processes, as these relationships often yield beneficial advice and support.
Evaluating Surety Providers
Choosing the right surety provider is a crucial step in the bidding process. Contractors must evaluate potential providers based on their financial stability, reputation in the industry, and the range of services offered. A strong surety provider can offer not only competitive rates but also valuable guidance throughout the bonding process.
Another effective strategy is to maintain accurate and up-to-date financial records. Surety companies require comprehensive financial documentation to assess a contractor's stability. Regularly updating financial statements, tax returns, and project performance records can help streamline the bonding process. Contractors who demonstrate financial responsibility are more likely to receive favorable terms and conditions on their bonds.
 Additionally, the financial implications of surety bonds cannot be overlooked. Contractors must demonstrate financial stability and a solid track record to obtain these bonds. Many surety companies require a detailed review of a contractor's financial statements, credit history, and project experience. Failing to present a comprehensive financial profile can lead to delays or outright rejections of bond applications, which could jeopardize the entire bidding process.
Contractors who prioritize safety are often viewed more favorably by surety companies, as a strong safety record indicates a commitment to responsible project management. This commitment not only protects workers but also safeguards the contractor's financial interests, as accidents can lead to costly delays and legal issues.
 Conclusion
In conclusion, understanding the relationship between surety bonds and effective reporting is essential for businesses seeking to secure lower rates. By implementing best practices, avoiding common pitfalls, and leveraging professional assistance, companies can enhance their credibility and reduce perceived risks. The benefits of adopting smart reporting strategies extend beyond just lower bond rates, fostering long-term relationships with surety providers and contributing to overall business success. As the surety bond landscape continues to evolve, businesses that prioritize transparency and accuracy in their financial reporting will undoubtedly position themselves for future growth and stability.