
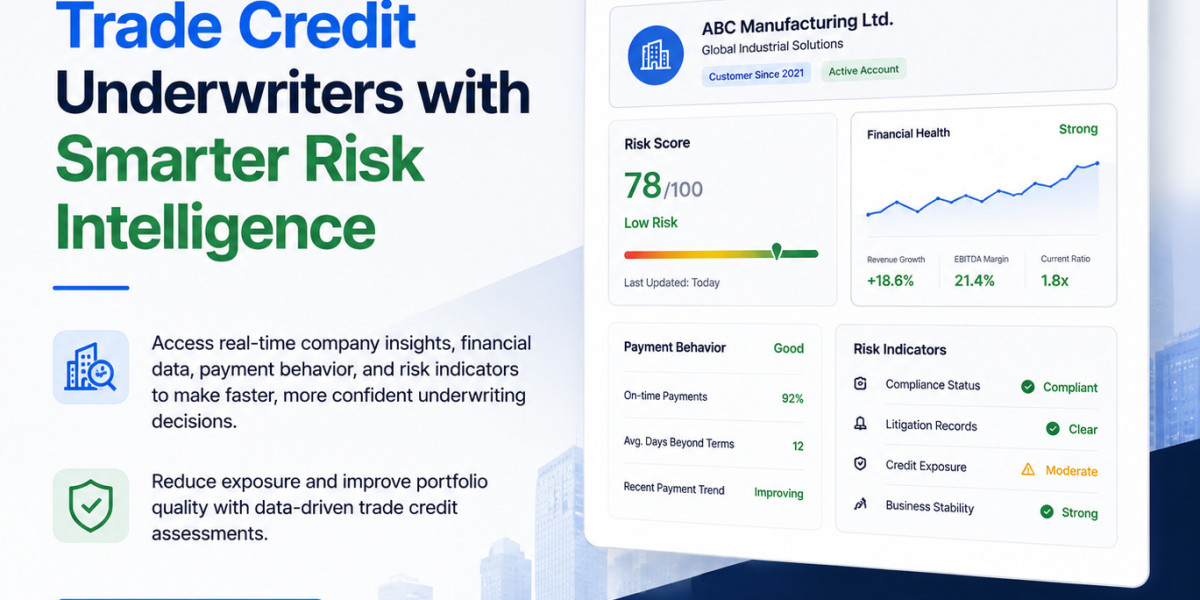
In today's digital economy, businesses and financial institutions must make fast, accurate, and data-driven credit decisions. Traditional credit assessment methods often involve manual reviews, lengthy approval processes, and inconsistent decision-making. As loan applications and customer expectations continue to grow, organizations need smarter solutions to manage credit risk efficiently.
A Credit Decision Engine helps businesses automate credit evaluation and lending decisions using predefined rules, analytics, and artificial intelligence (AI). Banks, NBFCs, fintech companies, insurance firms, and B2B enterprises use credit decision engines to improve operational efficiency, reduce risks, and accelerate approvals.
This guide explains everything businesses need to know about a Credit Decision Engine, including how it works, its benefits, key features, and best practices.
What is a Credit Decision Engine?
A Credit Decision Engine is a software platform that automates the process of assessing borrower creditworthiness and making lending decisions.
The system collects and analyzes data from multiple sources, including:
- Credit bureau reports
- Financial statements
- Bank account information
- Income records
- Business financial data
- Transaction history
Based on predefined credit policies and risk models, the engine can automatically approve, reject, or refer applications for manual review.
The primary goal is to improve the speed, consistency, and accuracy of credit decision-making.
Why is a Credit Decision Engine Important?
Modern businesses operate in a highly competitive lending environment where customers expect quick responses and seamless experiences.
Faster Decision-Making
Automated assessments significantly reduce loan processing times.
Improved Risk Management
Businesses can identify high-risk applicants before approving credit.
Reduced Operational Costs
Automation minimizes manual effort and administrative expenses.
Better Customer Experience
Faster approvals improve customer satisfaction and retention.
Consistent Credit Policies
A centralized decision engine ensures that all applications are evaluated using the same criteria.
How a Credit Decision Engine Works
Step 1: Data Collection
The system gathers applicant information from internal and external sources.
Common data points include:
- Credit scores
- Income details
- Employment information
- Banking transactions
- Existing liabilities
Step 2: Data Validation
The engine verifies submitted information and checks for inconsistencies or fraud indicators.
Automated verification helps improve data accuracy and compliance.
Step 3: Credit Risk Assessment
The platform evaluates creditworthiness using scoring models, business rules, and predictive analytics.
Risk factors may include:
- Repayment history
- Debt-to-income ratio
- Cash flow patterns
- Industry risk
- Business performance
Step 4: Decision Automation
Based on risk analysis, the Credit Decision Engine can:
- Approve applications
- Reject applications
- Request additional documentation
- Escalate cases for manual review
This process often occurs within seconds.
Step 5: Monitoring and Reporting
Modern systems continue monitoring customer behavior after approval and generate performance reports for management teams.
Key Features of a Credit Decision Engine
Automated Credit Scoring
Evaluates borrower risk using predefined scoring models.
Rule-Based Decisioning
Applies business policies consistently across all applications.
AI and Machine Learning
Advanced systems learn from historical data to improve decision accuracy.
Fraud Detection
Identifies suspicious activities and unusual application patterns.
Real-Time Processing
Supports instant credit assessments and approvals.
Integration Capabilities
Connects with CRM systems, ERP platforms, banking systems, and credit bureaus.
Benefits of a Credit Decision Engine
Enhanced Credit Risk Control
Businesses can reduce default rates through better risk assessment.
Increased Productivity
Automation allows teams to focus on strategic activities rather than manual reviews.
Higher Approval Efficiency
Applications are processed faster and more accurately.
Better Portfolio Quality
Improved decision-making helps maintain healthier loan portfolios.
Regulatory Compliance
Audit trails and automated documentation support compliance requirements.
Industries That Use Credit Decision Engines
Banking
Banks use decision engines to automate retail and commercial lending.
NBFCs
Non-Banking Financial Companies improve loan approval speed and risk management.
Fintech Companies
Digital lenders rely on automated decisioning to provide instant credit services.
Insurance Providers
Insurers use credit-based analytics for underwriting and risk evaluation.
B2B Enterprises
Companies assess customer creditworthiness before extending trade credit.
Challenges in Credit Decisioning
Data Quality Issues
Incomplete or inaccurate data can impact decision accuracy.
Regulatory Requirements
Credit decisions must comply with local and international regulations.
Cybersecurity Risks
Sensitive customer information requires strong data protection measures.
Changing Market Conditions
Risk models must be updated regularly to reflect economic changes.
Best Practices for Implementing a Credit Decision Engine
Use High-Quality Data Sources
Reliable data improves decision accuracy.
Combine Automation with Human Oversight
Complex cases may still require expert review.
Continuously Monitor Performance
Regular monitoring helps improve credit policies and models.
Update Risk Models Frequently
Economic and market conditions can affect borrower behavior.
Invest in Fraud Prevention
Advanced fraud detection tools strengthen lending security.
Conclusion
A Credit Decision Engine is a powerful tool that helps businesses automate credit assessments, improve risk management, and accelerate lending decisions. By leveraging AI, automation, and real-time analytics, organizations can make faster, more accurate, and more consistent credit decisions.
As digital lending continues to grow, businesses that implement modern credit decision engines will be better positioned to reduce risk, improve customer experiences, and maintain strong portfolio performance. For banks, NBFCs, fintech companies, and enterprises, adopting a robust credit decision engine is becoming an essential step toward smarter financial decision-making and sustainable growth.






