Blind Spot Object Detection System Market Trends, Demand, Growth & Future Outlook 2026–2034
Market Size
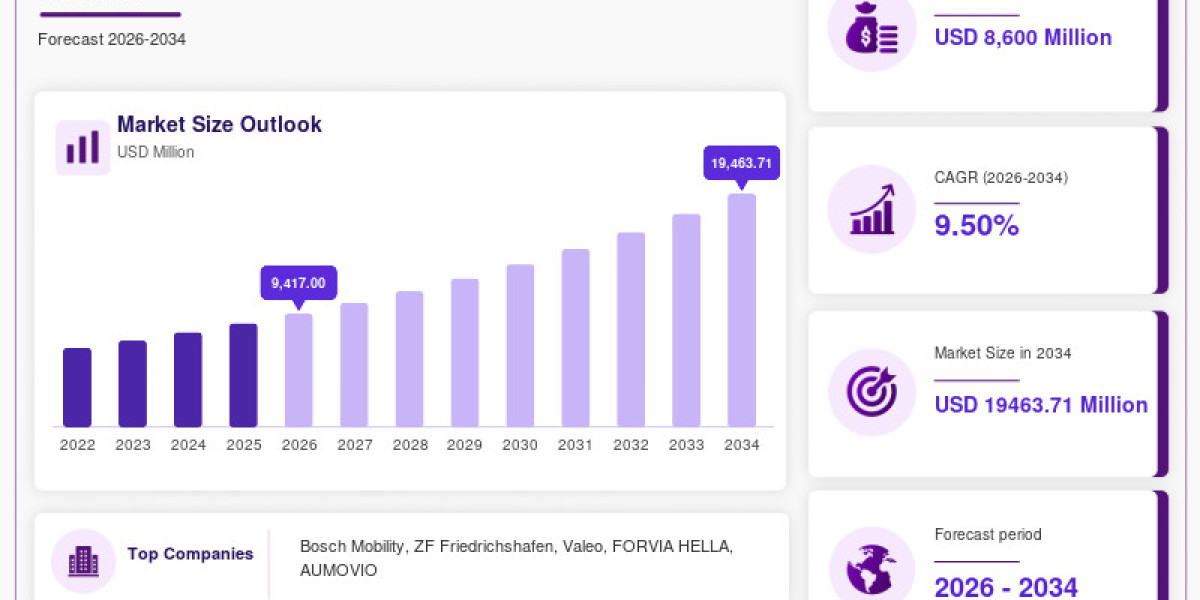
The global Blind Spot Object Detection System Market was valued at USD 8,600 million in 2025 and USD 9,417.00 million in 2026. The market is projected to reach USD 19,463.71 million by 2034, registering a CAGR of 9.50% during the forecast period.
Blind spot object detection systems comprise vehicle-mounted sensing and processing technologies that identify vehicles, motorcycles, bicycles, pedestrians, and other objects in areas that are difficult for drivers to observe directly or through conventional mirrors. These systems provide visual, acoustic, or haptic warnings and, in advanced configurations, can connect with braking or steering systems to help avoid or mitigate collisions.
Modern systems increasingly combine radar, cameras, ultrasonic sensors, LiDAR, electronic control units, and object-classification software. This combination enables manufacturers to improve detection accuracy while supporting multiple safety and driver-assistance functions.
Key Takeaways
The global market is projected to reach USD 19,463.71 million by 2034 at a 9.50% CAGR.
APAC accounted for 43% of the global market in 2026 and is projected to grow at 11.20% CAGR.
Radar represented 52% of the market in 2026 and is projected to grow at 9.10% CAGR.
Camera represented 25% of the market and is the fastest-growing major component at a 10.60% CAGR.
Passenger cars accounted for 73% of the market in 2026.
Commercial vehicles are the fastest-growing major vehicle category, with a projected CAGR of 12.10%.
Blind Spot Detection represented 48% of the market, while Moving-Off & Turn Assist is the fastest-growing major function at 11.80% CAGR.
Europe is projected to register a 9.40% CAGR, while North America is projected to grow at 8.90%.
Request Sample
Market Trends
The blind spot object detection system market is evolving from standalone warning systems toward integrated perception and active safety architectures. Radar, cameras, ultrasonic sensors, and other sensing technologies are increasingly connected through centralized electronic and software architectures.
A major trend is the reuse of sensing data across multiple vehicle functions. Blind spot detection can operate alongside lane-change assistance, rear cross-traffic alert, safe-exit warning, automated parking, moving-off information, and collision avoidance. Shared hardware and software can allow manufacturers to distribute sensor costs across multiple functions.
Another important trend is the increasing adoption of high-resolution radar and sensor fusion. Radar provides range, relative-speed, and direction information, while cameras contribute object classification and contextual information. This combination is particularly relevant for identifying pedestrians, cyclists, motorcycles, and vehicles in complex environments.
Commercial vehicles are also driving technology development. Trucks, buses, and trailers have extensive blind zones, increasing demand for systems capable of monitoring the entire vehicle and trailer combination.
Drivers
Expanding Regulatory Requirements
Regulatory requirements are increasing the installation base for blind-spot information systems. UNECE Regulation No. 151 establishes requirements for Blind Spot Information Systems, while EU Regulation 2019/2144 forms part of a broader vehicle-safety framework addressing vulnerable road users and advanced safety technologies.
These requirements increase OEM demand for side-perception technologies, vulnerable-road-user detection, automated warnings, integrated control units, software, and calibration services.
Increasing Vehicle Electronic Content
Blind-spot detection is increasingly integrated with lane-change assistance, rear cross-traffic alerts, parking functions, safe-exit systems, and collision-avoidance technologies.
Shared sensor architectures enable OEMs to use common hardware and software across several safety functions. As vehicle architectures become increasingly centralized and software-defined, sensing data can be reused across multiple driver-assistance and automated-driving functions.
Growth of Commercial Vehicles, EVs, and Advanced Vehicle Architectures
Large vehicles have significant visibility limitations, particularly during turning, lane changes, and moving-off maneuvers. This creates demand for corner radar and broader 360-degree perception systems.
At the same time, electric and software-defined vehicles are incorporating increasingly sophisticated sensor architectures, widening the addressable market for blind spot object detection technologies.
Restraints
Sensor Calibration and Integration Complexity
Modern blind-spot systems depend on accurate sensor positioning, orientation, calibration, and communication with vehicle-control systems. Differences in mounting angle or vehicle geometry can affect detection zones and object localization.
As systems become more integrated and software-defined, OEMs and service providers require increasingly sophisticated calibration equipment, diagnostic capabilities, and lifecycle support.
False Positives and Environmental Conditions
Blind spot systems must distinguish relevant road users from stationary infrastructure, parked vehicles, barriers, and other non-threatening objects. Sensor contamination, occlusion, complex urban environments, and challenging object geometries can affect detection performance.
Improving detection accuracy therefore requires more sophisticated algorithms, sensor fusion, processing capabilities, and software validation.
Opportunities
High-Resolution Radar and Sensor Fusion
The market is moving beyond warning indicators toward systems that can contribute to active collision prevention. Integrated radar, camera, braking, and steering architectures can enable systems to progress from driver alerts toward assisted collision avoidance.
This creates opportunities for suppliers capable of combining sensing, perception, software, and vehicle-control technologies within integrated safety architectures.
Two-Wheelers and Emerging-Market Vehicle Platforms
Radar-based blind-spot and lane-change functions are expanding into motorcycles and scooters. Partnerships involving Valeo and Hero MotoCorp demonstrate development of advanced rider-assistance systems across entry-level, premium, and electric two-wheelers.
Commercial-vehicle ADAS localization also provides opportunities in emerging markets. Cost-optimized architectures can support adoption where vehicle volumes are high but the installed cost of premium multi-sensor ADAS remains a constraint.
Market Segmentation Analysis
The Blind Spot Object Detection System Market is segmented by component, vehicle type, function, and region.
By Component
Radar
Radar accounted for 52% of the global market in 2026 and is projected to register a 9.10% CAGR. Radar remains a central sensing technology because it can provide information on object distance, relative speed, and movement direction across demanding driving conditions.
Corner and side radar systems are increasingly used for blind-spot detection and surrounding-object monitoring, frequently alongside cameras and other sensors.
Camera
Camera accounted for 25% of the market in 2026 and is projected to register a 10.60% CAGR, making it the fastest-growing major component category.
Cameras complement radar by providing object classification and contextual information. Radar-camera fusion is increasingly important for distinguishing pedestrians, cyclists, motorcycles, and vehicles in complex traffic environments.
Other Components
The remaining component categories include Ultrasonic and LiDAR & Other Sensors. The supplied source does not provide separate market shares or CAGRs for these categories.
Vehicle Type Analysis
Passenger Cars
Passenger cars accounted for 73% of the global market in 2026 and are projected to register a 9.10% CAGR. Blind-spot detection is increasingly bundled with lane-change assistance, rear cross-traffic alert, parking, and broader ADAS packages.
Commercial Vehicles
Commercial vehicles accounted for 22% of the market in 2026 and are projected to register a 12.10% CAGR, making them the fastest-growing major vehicle category.
Trucks, buses, and large trailers have substantial blind areas, particularly during turning, lane changes, and moving-off maneuvers. This creates strong demand for systems capable of monitoring side areas and vulnerable road users.
Two-Wheelers
Two-wheelers represent an expanding application area as manufacturers introduce radar- and camera-based rider assistance systems. The supplied source does not provide a separate market share or CAGR for this category.
Function Analysis
Blind Spot Detection
Blind Spot Detection accounted for 48% of the global market in 2026 and is projected to register a 9.20% CAGR. It remains the foundational safety function, monitoring adjacent lanes and areas that are difficult to observe using mirrors alone.
Warnings can be delivered through mirror indicators, instrument displays, acoustic signals, or haptic feedback.
Moving-Off & Turn Assist
Moving-Off & Turn Assist accounted for 18% of the market in 2026 and is projected to register an 11.80% CAGR, making it the fastest-growing major function category.
The function is particularly relevant to trucks and buses, where pedestrians and cyclists can enter large side and front blind zones during low-speed maneuvers.
Other Functions
The remaining functions include Lane Change Assist, Rear Cross-Traffic Alert, and Safe Exit & Dooring Detection. The supplied source does not provide separate market shares or CAGRs for these functions.
Regional Analysis
APAC
APAC accounted for 43% of the global market in 2026 and is projected to register an 11.20% CAGR, making it the largest and fastest-growing regional market.
The region combines large-scale vehicle production with expanding automotive-electronics manufacturing and localized ADAS development. China, Japan, South Korea, and India remain important vehicle markets as well as engineering and component-production centers.
North America
North America is projected to register an 8.90% CAGR. Growth is supported by passenger vehicles, commercial-vehicle fleets, highway transportation, and increasing integration of radar-based ADAS.
The region also supports an aftermarket and calibration ecosystem because vehicles equipped with advanced radar systems require specialized repair and sensor-alignment capabilities.
Europe
Europe is projected to register a 9.40% CAGR. Growth is supported by established ADAS adoption, regulatory requirements, automotive engineering capabilities, and commercial-vehicle safety programs.
The region is also an important technology-development center for high-resolution radar and integrated radar-camera architectures.
Middle East and Africa
The Middle East and Africa market is projected to register a 7.80% CAGR. Commercial vehicles, logistics fleets, road infrastructure, and increasing adoption of modern vehicle-safety technologies support demand.
Heavy trucks and buses represent an important application area because of their substantial side-visibility limitations.
LATAM
LATAM is projected to register an 8.50% CAGR. Automotive manufacturing in Mexico and Brazil, commercial fleets, road transportation, and growing adoption of electronic safety systems support market development.
Scalable ADAS architectures can also be adapted to differing cost and regulatory requirements across regional vehicle platforms.
Competitive Landscape
The market includes automotive Tier 1 suppliers, radar specialists, ADAS software companies, sensor manufacturers, and commercial-vehicle safety-system providers.
Bosch Mobility offers passenger-car and heavy-commercial-vehicle blind-spot systems using radar and ultrasonic sensing. ZF has a broad commercial-vehicle safety portfolio incorporating radar, cameras, braking, and steering technologies. Valeo is developing corner-radar platforms supporting blind-spot detection, lane-change assistance, rear cross-traffic alert, parking, and advanced-driving functions.
Competition is increasingly focused on sensor performance, software integration, object classification, calibration, multi-function architectures, and the ability to support both passenger and commercial vehicles.
Key Market Players
Bosch Mobility
ZF Friedrichshafen
Valeo
FORVIA HELLA
AUMOVIO
Mobileye
Aptiv
Magna International
DENSO
Autoliv
Hitachi Astemo
NXP Semiconductors
Harman International
Panasonic Automotive Systems
Hyundai Mobis
Recent Developments
June 2026 – ZF Expanded Safety and Motion Systems
ZF showcased new safety and motion systems for software-defined commercial vehicles. The architecture uses radar and camera sensors positioned around trucks and trailers to provide continuous perception and support integrated safety functions.
June 2026 – Valeo Secured Next-Generation Radar Contract
Valeo secured a major contract with a North American electric-vehicle manufacturer for next-generation corner-radar technology. The platform combines hardware and embedded software and supports Blind Spot Detection, Lane Change Assist, Rear Cross-Traffic Alert, and advanced parking functions.
Market Segments
By Component
Radar
Camera
Ultrasonic
LiDAR & Other Sensors
By Vehicle Type
Passenger Cars
Commercial Vehicles
Two-Wheelers
By Function
Blind Spot Detection
Lane Change Assist
Rear Cross-Traffic Alert
Safe Exit & Dooring Detection
Moving-Off & Turn Assist
By Region
North America
Europe
APAC
Middle East and Africa
LATAM
Frequently Asked Questions
What is the size of the Blind Spot Object Detection System Market?
The global Blind Spot Object Detection System Market was valued at USD 8,600 million in 2025 and USD 9,417.00 million in 2026. It is projected to reach USD 19,463.71 million by 2034, registering a 9.50% CAGR.
What is driving the growth of the Blind Spot Object Detection System Market?
Growth is supported by expanding regulatory requirements, increasing vehicle electronic content, the integration of multiple safety functions, growth in commercial vehicles and EVs, and the development of advanced radar and sensor-fusion architectures.
Which component holds the largest market share?
Radar held the largest component share, accounting for 52% of the global market in 2026.
Which vehicle type is projected to grow at the highest CAGR?
Commercial Vehicles are projected to register the highest CAGR among the major vehicle categories at 12.10% during the forecast period.
Which region holds the largest market share and which region has the highest CAGR?
APAC held the largest regional share at 43% in 2026 and is also projected to have the highest regional CAGR at 11.20%.
Conclusion
The Blind Spot Object Detection System Market is expanding as vehicle manufacturers integrate increasingly sophisticated sensing and driver-assistance technologies. Regulatory requirements, rising vehicle electronic content, commercial-vehicle safety needs, EV adoption, and software-defined vehicle architectures are supporting demand.
Radar remains the leading component, while cameras are expanding rapidly as part of multi-sensor perception systems. Passenger cars represent the largest vehicle category, while commercial vehicles are experiencing faster growth because of their substantial blind zones and increasing safety requirements. Moving-Off & Turn Assist is also gaining importance as manufacturers focus on vulnerable-road-user protection.
Regional growth is particularly strong in APAC, supported by its large vehicle-production base and expanding ADAS development. The continued integration of radar, cameras, braking, steering, and software is expected to broaden the role of blind spot systems from driver warning toward more comprehensive active safety and collision-prevention architectures.
Report URL
https://reedintelligence.com/market-analysis/blind-spot-object-detection-system-market