


In at this time's financial panorama, gaining entry to credit score can usually feel like navigating a complex maze, particularly for people with much less-than-perfect credit score histories. The strategy of acquiring a loan with bad credit presents a substantial problem, however understanding the nuances of this endeavor can empower individuals to make knowledgeable choices. This observational research article explores the realities faced by borrowers with bad credit, highlighting the accessible options, the affect of credit score scores on loan alternatives, and the ethical concerns surrounding excessive-curiosity lending practices.
Understanding Bad Credit
Bad credit typically refers to a credit score that falls under the threshold thought-about acceptable by lenders, which is often around 620 on the FICO scale. Individuals could discover themselves on this predicament for various reasons, together with a history of missed payments, high credit utilization, or defaults on previous loans. The consequences of bad credit are significant, typically limiting entry to loans, credit score cards, and even housing opportunities. Consequently, those with bad credit should navigate the monetary system with heightened warning and consciousness.
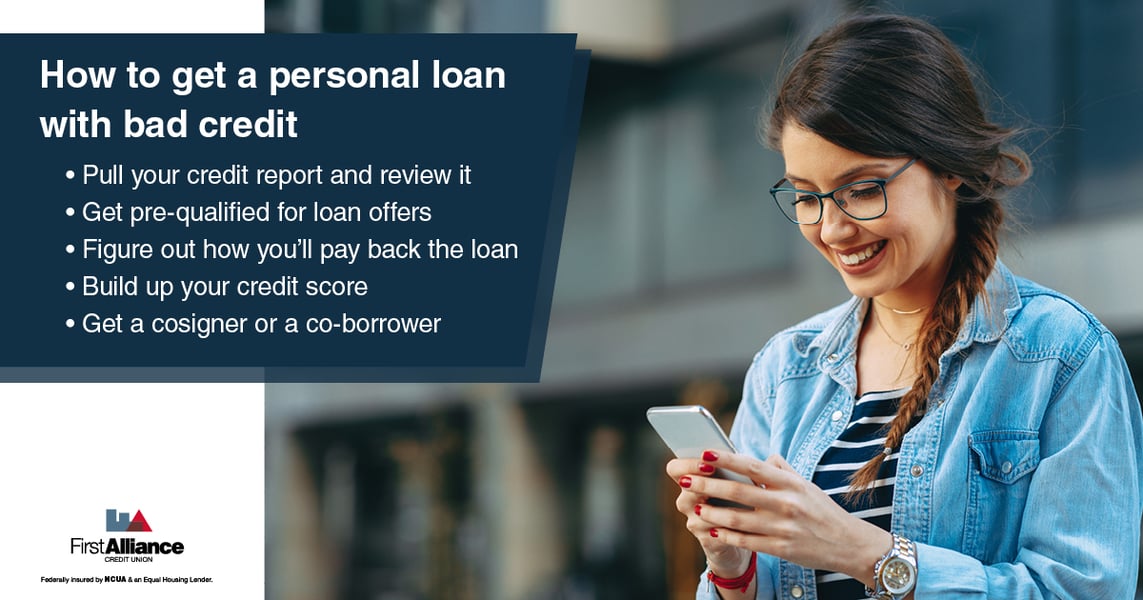
The Demand for Loans
Regardless of the challenges, the demand for loans persists among people with bad credit. Should you loved this article and you would want to receive details with regards to Bnkode kindly visit the web page. Widespread motivations for looking for such loans include urgent medical expenses, automobile repairs, or unexpected life events that necessitate rapid financial help. Observations in numerous communities reveal a wealthy tapestry of various applicant backgrounds, every with distinctive stories driving their want for monetary help. This shows that bad credit is just not solely a reflection of monetary irresponsibility, however typically a product of unforeseen circumstances.
Loan Choices for Bad Credit Borrowers
Whereas the journey to securing a loan with bad credit could be arduous, a number of choices exist for borrowers prepared to discover different pathways.
- Subprime Lenders: These lenders specialize in offering loans to excessive-danger people. While they provide access to credit score that traditional banks could deny, subprime loans usually include higher interest charges and less favorable terms.
- Credit score Unions: Some credit score unions are extra lenient than traditional banks relating to lending. They could offer personal loans to members with bad credit at extra favorable charges than these of subprime lenders.
- Peer-to-Peer Lending: Platforms that facilitate peer-to-peer lending connect borrowers immediately with individual lenders. These platforms may consider the borrower's overall financial image relatively than solely their credit rating.
- Secured Loans: People with bad credit can consider secured loans, which require collateral. By providing an asset as safety, borrowers might acquire access to raised loan phrases, as lenders perceive much less danger.
The Role of Credit score Scoring in Loan Approval
All through our exploration of loan acquisition with bad credit, probably the most notable issue influencing approval stays the credit score rating. Nonetheless, many lenders are beginning to undertake different methods for evaluating a borrower's creditworthiness. This consists of contemplating earnings, employment stability, and different indicators of monetary accountability. Anecdotal proof collected from conversations with loan officers reveals a growing curiosity in assessing a borrower's capability to repay relatively than solely relying on numerical scores.
Such insights are essential for individuals with bad credit, as they recommend that demonstrating monetary stability or dedication could enhance their possibilities of securing a loan. Particularly, these engaged in discussions about their monetary situations reported feeling more empowered when lenders took the time to know their circumstances slightly than merely conducting a transaction based mostly on a score.
Ethical Concerns and Challenges
Whereas the demand for loans persists amongst people with bad credit, moral concerns surrounding high-curiosity lending practices are paramount. Observations point out that some subprime lenders exploit weak borrowers, imposing exorbitant interest charges that further entrench them in a cycle of debt. Regulatory efforts have been applied in various jurisdictions to protect consumers from predatory lending practices, but challenges remain.
As people with bad credit often have restricted monetary schooling, they could not absolutely grasp the long-time period impacts of high-interest loans. Conversations with borrowers reveal a mixture of remorse and urgency as they navigate these contracts, emphasizing the necessity for better monetary literacy initiatives. Our observations illuminate the significance of lenders appearing responsibly and transparently whereas creating honest lending practices that prioritize borrower wellbeing.
The Significance of Financial Literacy
The need for monetary literacy among individuals with bad credit can't be overstated. Observations indicate that many borrowers do not totally understand the implications of borrowing terms or how to improve their credit scores. Packages aimed toward enhancing financial schooling are therefore essential for empowering individuals to make informed decisions that serve their finest pursuits.
In some communities, native organizations and non-profits have stepped in to provide financial schooling and resources for individuals struggling with financial points. These initiatives have proven promise in fostering accountable borrowing and proactive credit score management, contributing to a gradual improvement in financial literacy among the target demographic.
Conclusion
Acquiring a loan with bad credit is undeniably difficult, however our observations spotlight a fancy actuality crammed with each obstacles and opportunities. As people navigate the panorama of borrowing, understanding the accessible options and the position of credit scoring is crucial. Moreover, recognizing the ethical implications of lending practices and the significance of financial literacy can facilitate larger empowerment for individuals going through credit challenges.
In the end, as awareness grows and lenders undertake extra responsible practices, there is potential for a extra equitable financial system that serves the various wants of all borrowers, no matter their credit histories. In this evolving panorama, people with bad credit can discover hope and support, paving the way toward improved monetary futures.





